Insurance
The $60 Billion Oversight: Why Your Benefits Package Protects Your Body, Not Your Career
October 23, 2026
Every November during Open Enrollment, millions of professionals do the responsible thing. You review your benefits portal, check the box for Short-Term and Long-Term Disability (STD and LTD) insurance, and breathe a sigh of relief knowing your paycheck—the engine behind your mortgage, investments, and lifestyle—is protected. Except there is a massive structural blind spot in that plan.
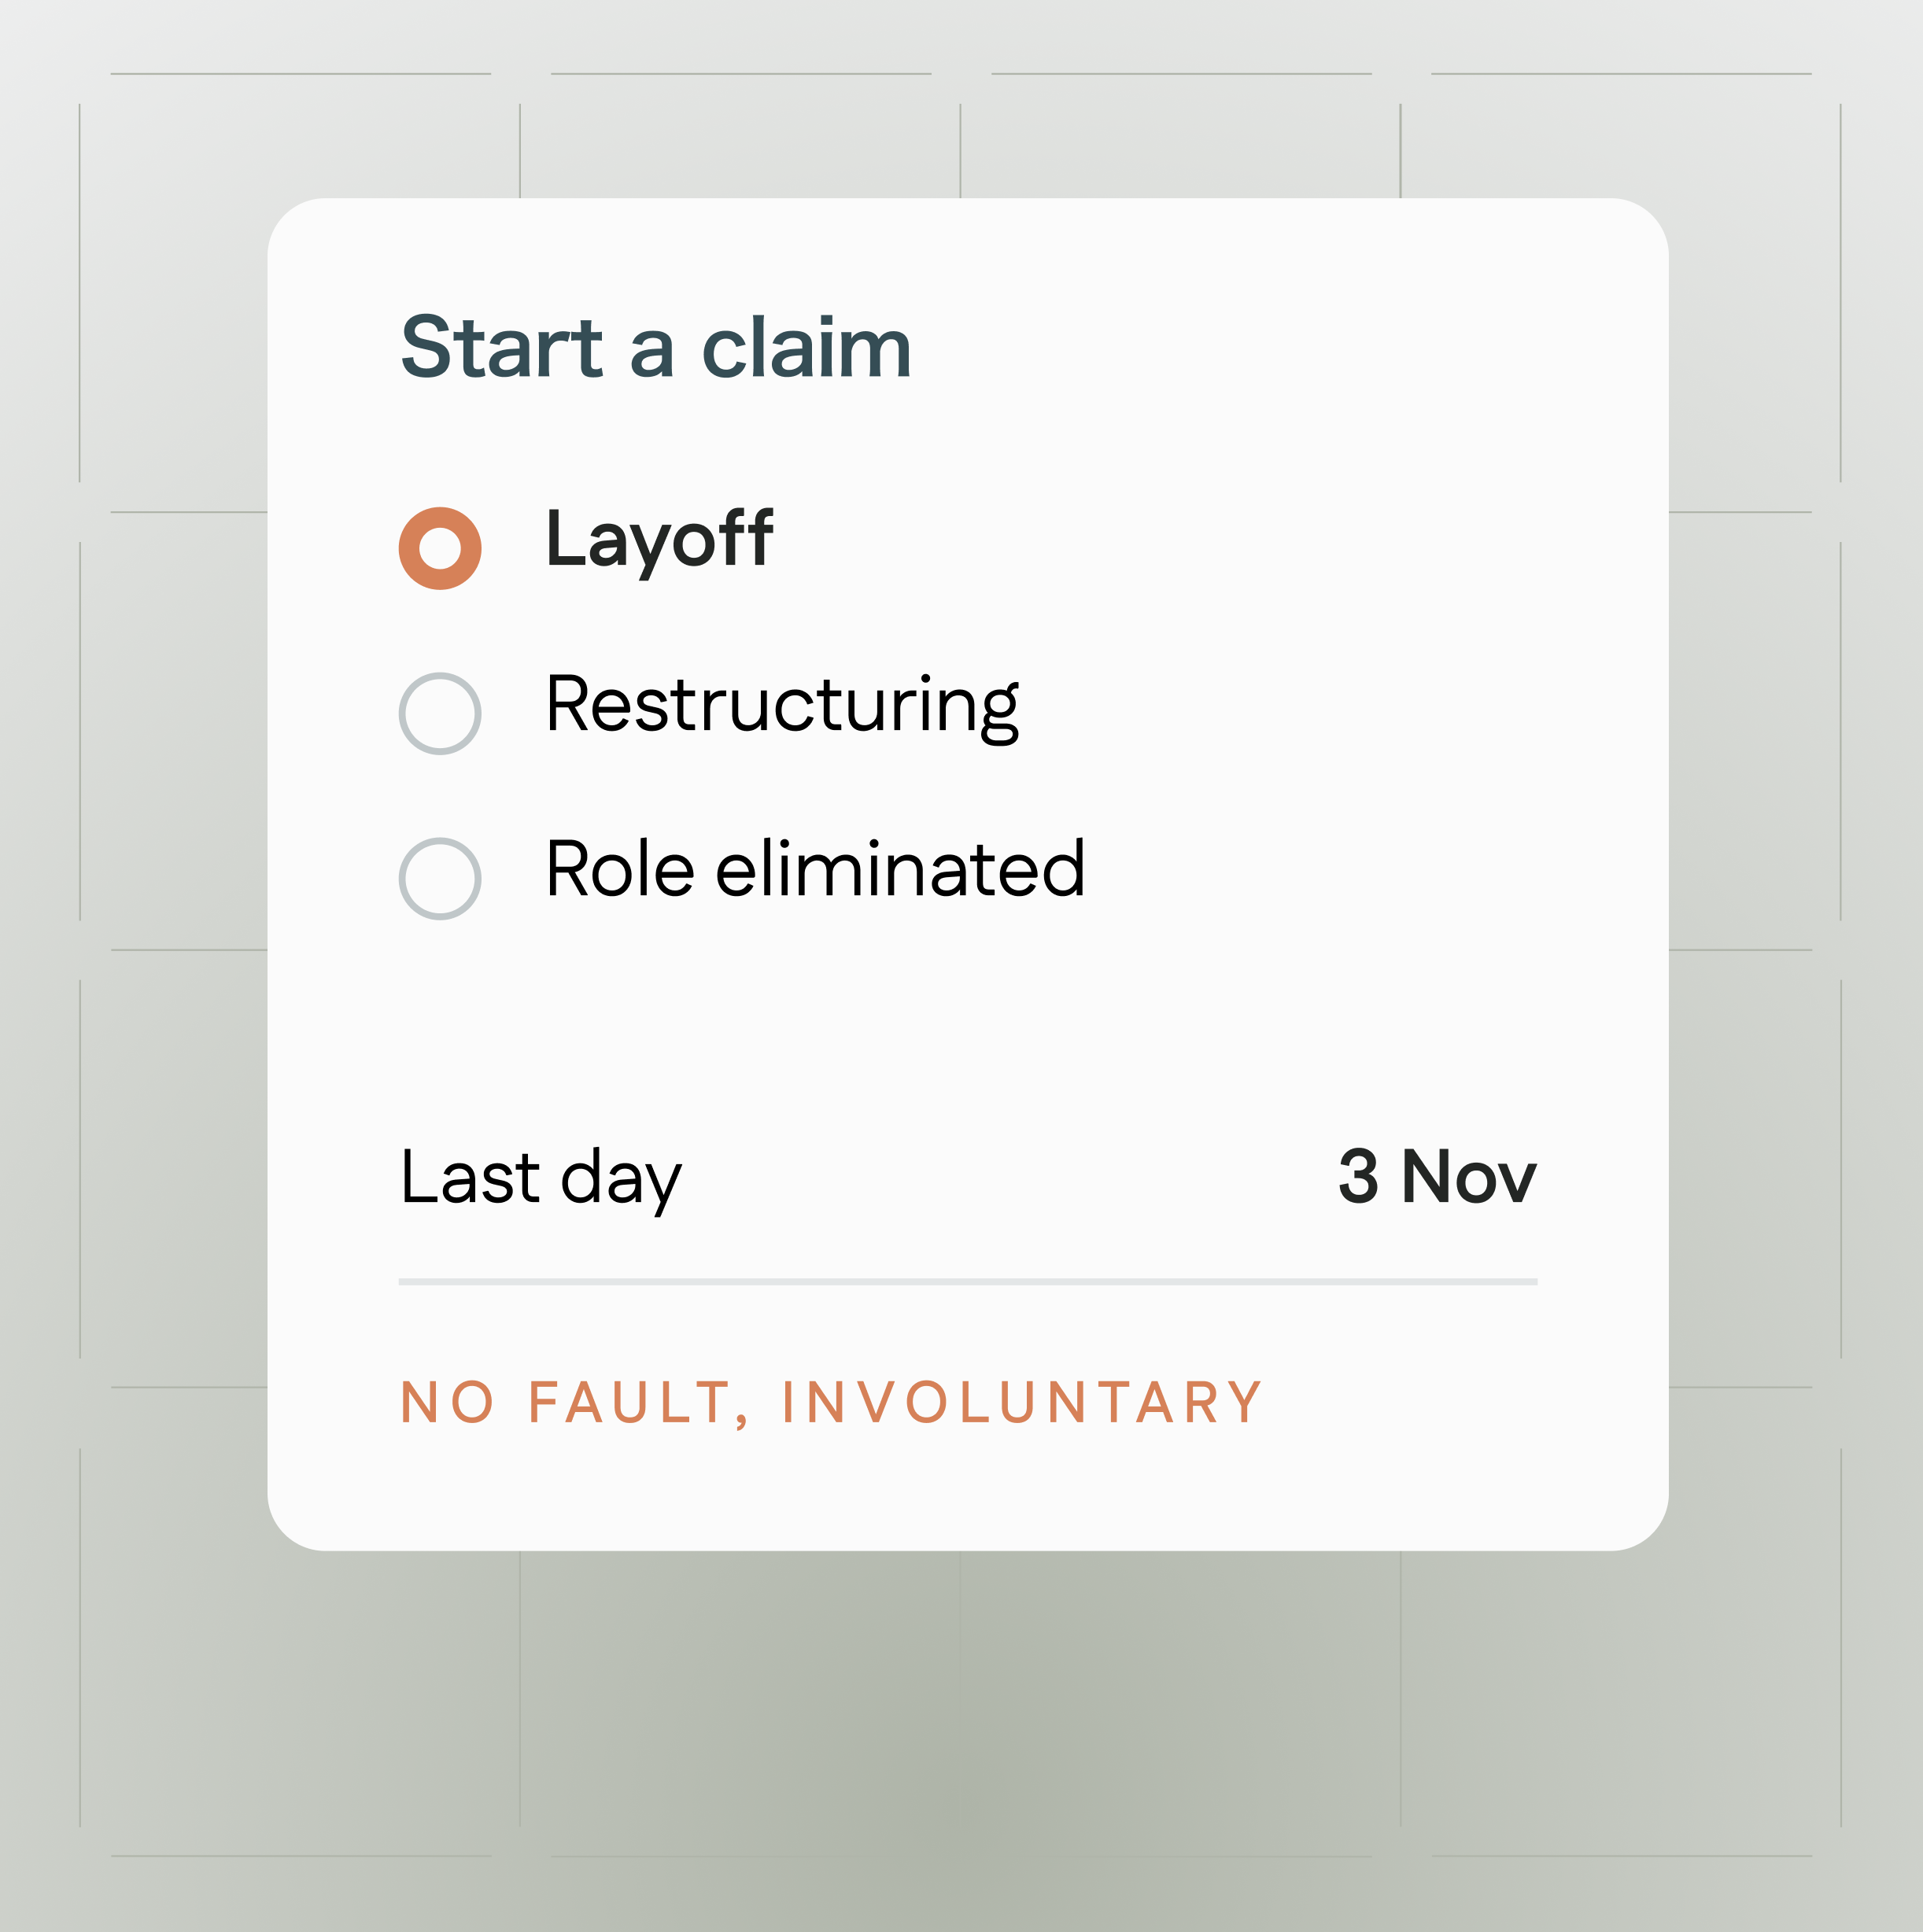
Yet the single biggest threat to a modern professional’s cash flow—a no-fault corporate layoff—is completely excluded from your standard insurance portfolio. Here is the breakdown every W-2 earner needs to see:
Traditional Short-Term and Long-Term Disability (STD/LTD) policies only underwrite biological risk. They are designed to pay out if an illness or physical injury stops you from working. If a corporate restructuring, merger, or Reduction in Force (RIF) eliminates your position tomorrow, disability insurance pays nothing. Traditional disability insurance only protects your income if your body fails. It pays zero dollars if your employer’s strategy fails.
For a healthy 35-year-old VP, software engineer, or corporate director, what is more likely to interrupt your cash flow over the next five years: a debilitating physical injury, or an unexpected corporate restructuring? While the global income protection market is projected to exceed $60 billion by 2030, the overwhelming majority of that capital is concentrated in traditional disability coverage—leaving healthy, able-bodied professionals completely exposed to the most common career peril of the modern economy: the no-fault layoff.
To understand why your benefits package leaves you exposed, it helps to look at how the insurance industry divides risk:
Most professionals assume that if an economic peril hits, State Unemployment Insurance (UI) will step in where disability coverage stops.
When an economic risk hits, high earners fall onto State Unemployment Insurance (UI)—a 1930s system capped at roughly $200 to $500 per week in most states ($275/wk in FL, $378/wk in VA, $577/wk in TX). For a six-figure earner, State UI covers under 15% of monthly fixed obligations, forcing nearly 48% of high earners who live paycheck to paycheck into a sudden liquidity crunch.
True financial resilience requires covering all three legs of the income-protection stool:
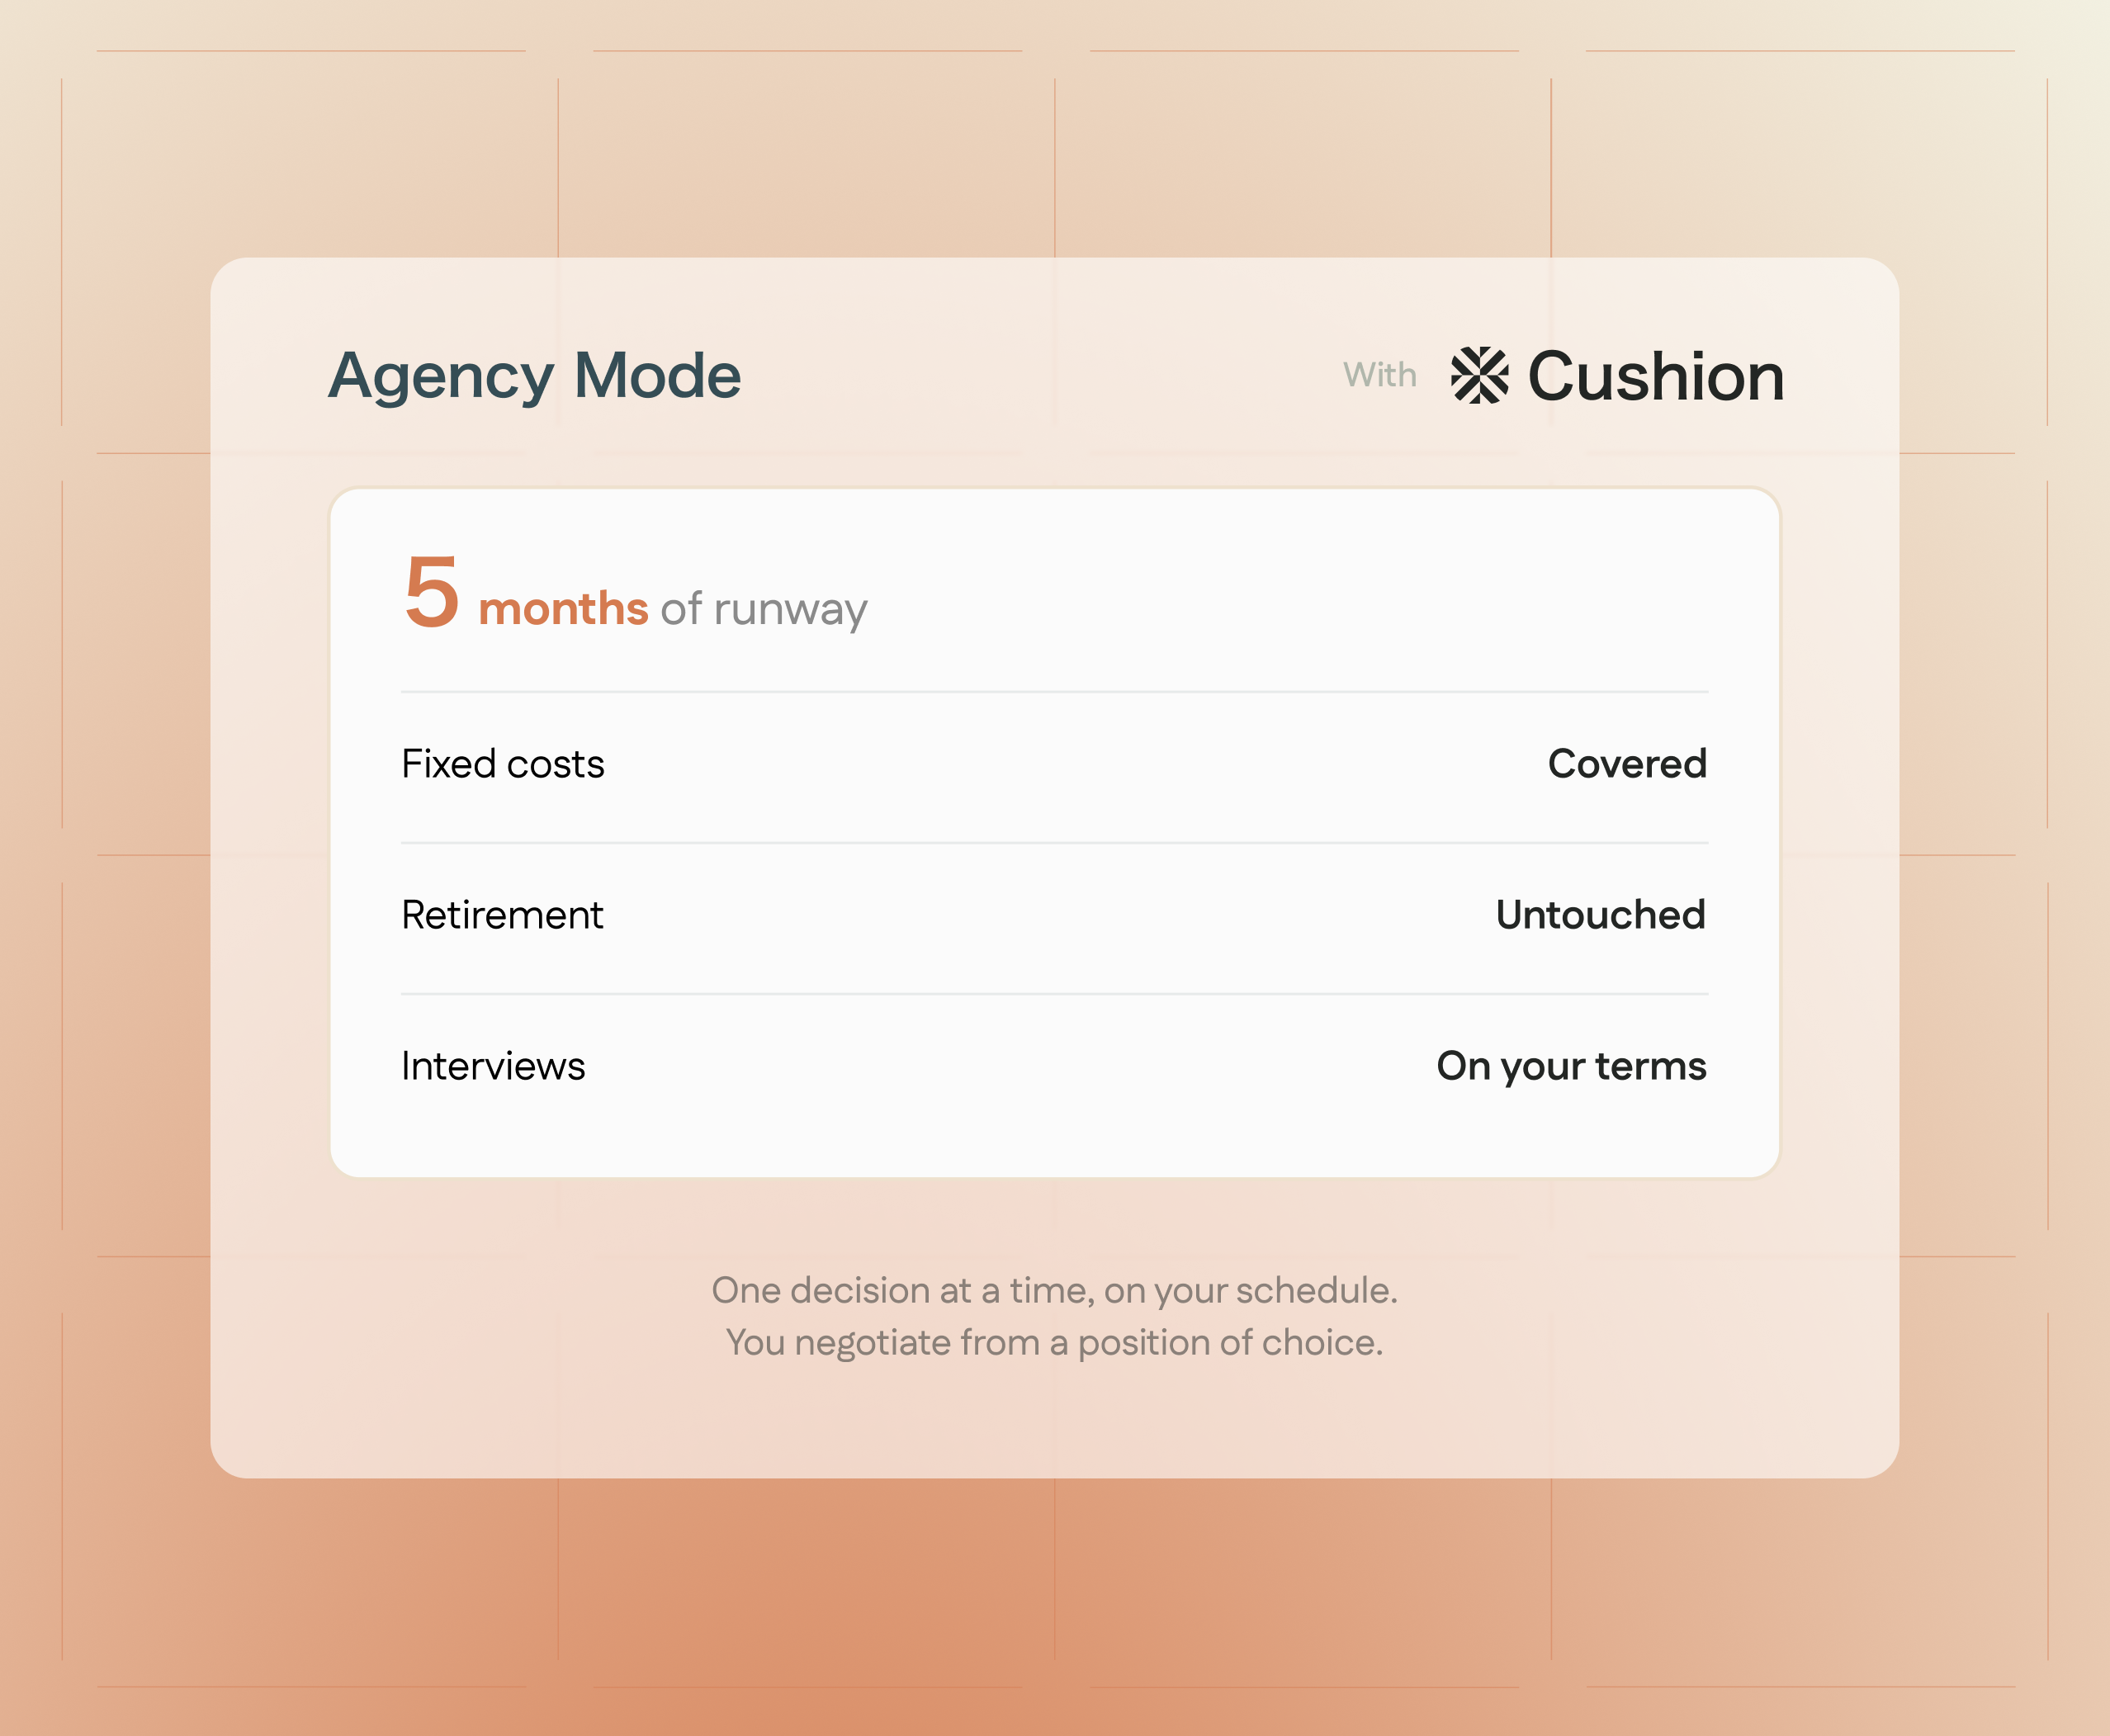
Cushion is Private Supplemental Involuntary Unemployment Insurance (PSIUI). Engineered as a standalone, portable policy, it acts as high-performance shock absorption for your cash flow:
You’ve already protected your income against a broken leg. Isn't it time you protected it against a corporate restructuring?